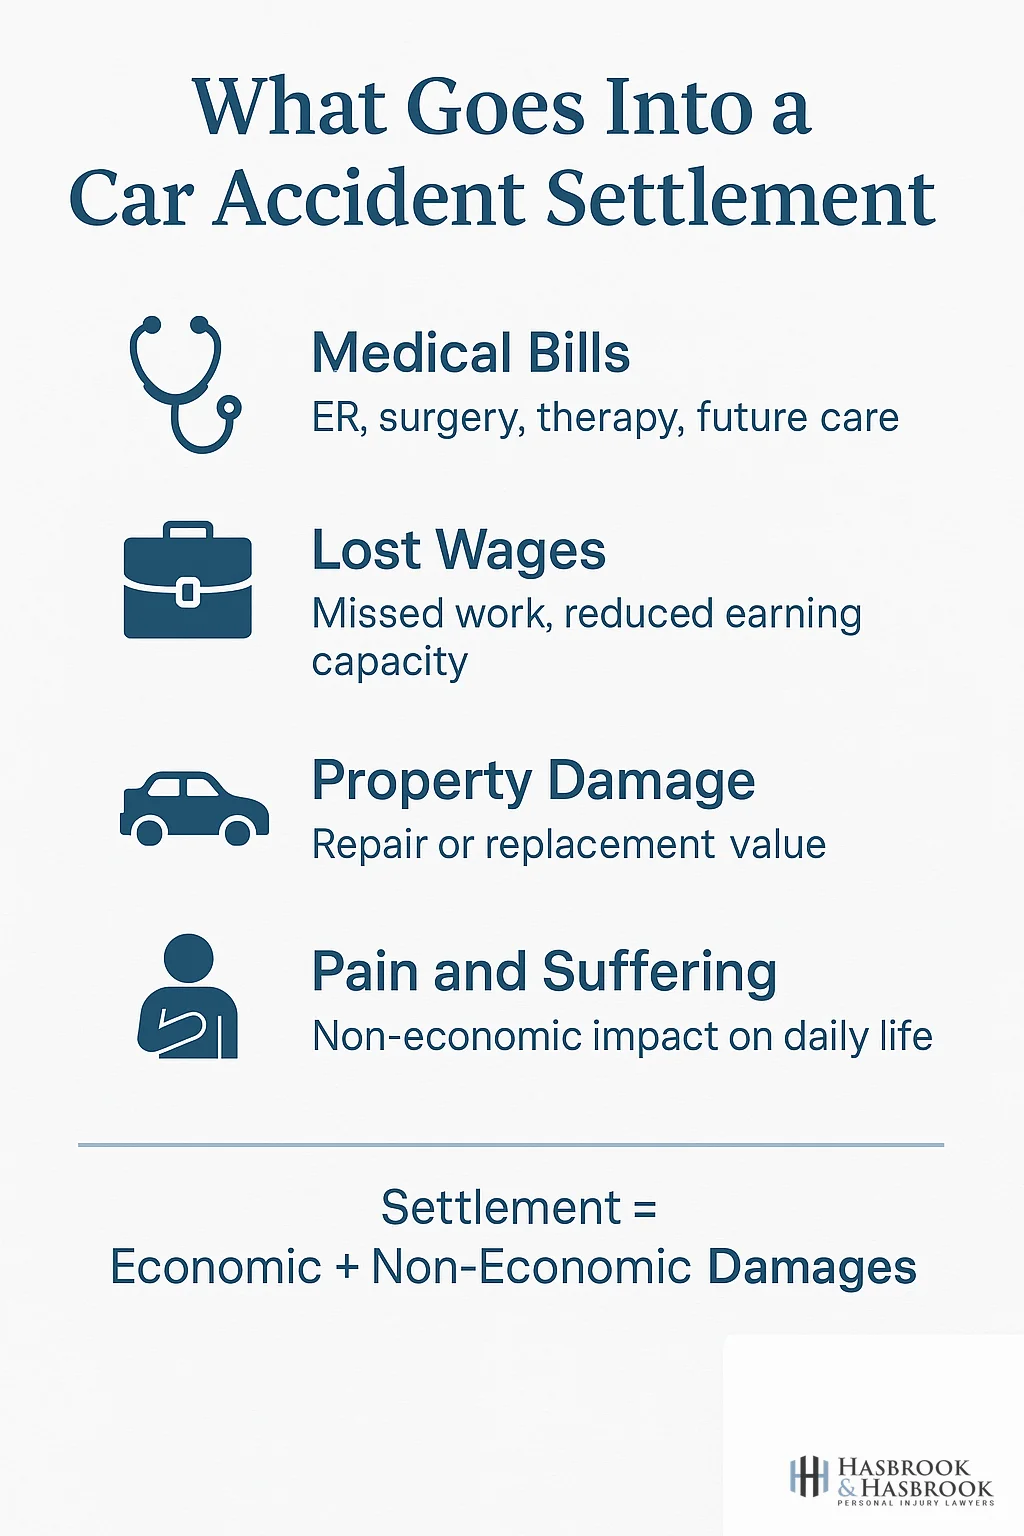
An Oklahoma car accident settlement equals your economic damages (medical bills, lost wages, property damage) plus non-economic damages (pain and suffering), minus your share of fault. Under Oklahoma’s comparative negligence rule, 23 O.S. § 13, you recover nothing if your fault exceeds 50 percent. Attorney fees, case costs, and medical liens further reduce your net payment.
After a car accident in Oklahoma, two numbers matter: the gross value of your claim, and what you actually keep after fees, costs, and liens are deducted. This page explains how each element is valued, what the settlement process looks like from demand through payment, and what realistic net recovery looks like in practice. For dollar ranges, see realistic compensation ranges for Oklahoma car crashes. For coverage denials or lowball offers, see disputes that commonly stall a car accident claim.
What factors determine the value of your Oklahoma car accident settlement?
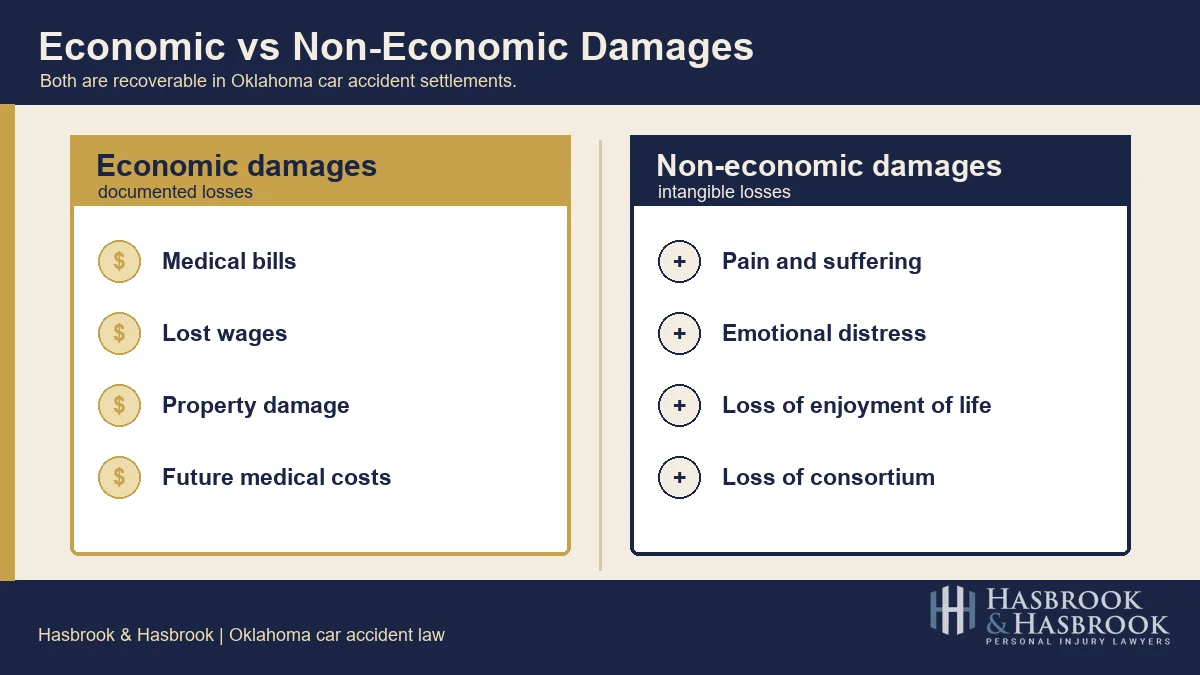
Oklahoma car accident settlements compensate for two categories of losses: economic damages you can document with receipts, and non-economic damages for pain, suffering, and life disruption. How much each category contributes depends on injury severity, available evidence, policy limits, and how much fault is attributed to you.
Economic damages
Economic damages are documented, dollar-quantifiable losses: emergency care, surgery, imaging, hospitalization, and physical therapy, plus future medical costs projected by a physician or life-care planner, paychecks missed while you recover from a wreck, reduced future earning capacity, and the cost of repairing or replacing your vehicle.
Non-economic damages
Non-economic damages cover losses receipts cannot capture, including pain and suffering, emotional distress, and loss of enjoyment of activities. Oklahoma does not cap non-economic damages in most car accident cases (see the state-law section below for the exceptions). See our page on how the multiplier method values pain and suffering for the two calculation approaches insurers and attorneys use.
Insurance policy limits
The at-fault driver’s policy caps what you can collect from that carrier. For policies issued or renewed since April 1, 2005, Oklahoma requires minimum coverage of $25,000 per person and $50,000 per accident for bodily injury, plus $25,000 for property damage, shorthanded 25/50/25, under 47 O.S. § 7-103 (see the Oklahoma Insurance Department’s consumer guide to auto coverage). When damages exceed those limits, other sources may include your own underinsured motorist coverage, the at-fault driver’s employer, or the driver personally.
Severity of injuries, medical costs, and Oklahoma’s paid-not-incurred rule
Injury severity is the largest single driver of settlement value. A soft-tissue strain resolving in six weeks generates limited bills and no lasting impairment; a cervical fracture requiring surgery and rehabilitation generates years of ongoing costs and a substantial pain and suffering component. For serious or permanent injuries, your attorney may engage a life-care planner to project future medical needs.
Oklahoma applies a paid-not-incurred rule under 12 O.S. § 3009.1: at trial, the recoverable amount for medical bills is generally limited to what was actually paid, not the original billed amount before insurance write-offs. Adjusters apply this same rule when evaluating your bills. Our attorneys use a paid-versus-incurred evidentiary framework to analyze how this rule applies to each client’s bills.
If you carry Medical Payment Coverage (MedPay), those amounts can still be included in your demand; the at-fault driver’s insurer does not get credit for coverage you purchased.
How pain and suffering is calculated in an Oklahoma settlement
Two methods are commonly used to calculate pain and suffering in settlement negotiations:
- Multiplier method: Total economic damages are multiplied by a factor, typically 1.5 to 5, based on injury severity, treatment duration, and permanence of any impairment. Serious spinal injuries with long-term restrictions may warrant a multiplier of 3 or higher; soft-tissue strains that resolved without residual impairment typically fall below 2.
- Per diem method: A daily dollar rate is assigned for each day from the accident through the point your treatment plateaus. This can yield higher results in extended-recovery cases, but adjusters often resist it.
Your attorney argues for the approach that best reflects your experience, backed by medical records, treatment gaps (or the lack of them), and how the injury changed your daily routine.

Oklahoma state laws that affect your car accident settlement
Several Oklahoma statutes directly shape what you can recover, when you must act, and how fault affects your payout.
Statute of limitations. Under 12 O.S. § 95, you generally have two years from the accident date to file a personal injury lawsuit, or the claim is barred. See our page on the limited tolling exceptions that can pause this clock.
Comparative negligence. Under 23 O.S. § 13, your damages are reduced by your percentage of fault, and you recover nothing above 50 percent fault. See our page on how Oklahoma juries split fault between drivers.
The noneconomic damages cap. A prior cap under former 23 O.S. § 61.2 was struck down as unconstitutional in Beason v. I.E. Miller Services, 2019 OK 28 (a special-law violation, Art. 5, § 46). Effective September 2025, a new $500,000 noneconomic damages cap applies under 23 O.S. § 61.3, but it does not apply at all if a jury finds you suffered a permanent and severe physical injury, including a substantial physical abnormality or disfigurement, loss of use of a limb, or substantial impairment to a major body organ or system; in that situation there is no noneconomic-damages limit. The new cap has not yet reached the Oklahoma Supreme Court, so whether Beason extends to it remains open.
Punitive damages. Under 23 O.S. § 9.1, a jury may award up to $100,000 (or actual damages, whichever is greater) for reckless disregard, up to $500,000 (or twice actual damages) for intentional and malicious conduct, or an uncapped amount for life-threatening conduct. Uncommon in standard collisions. See when reckless or intentional conduct opens the door to punitive damages.
The insurance process for filing an Oklahoma car accident claim
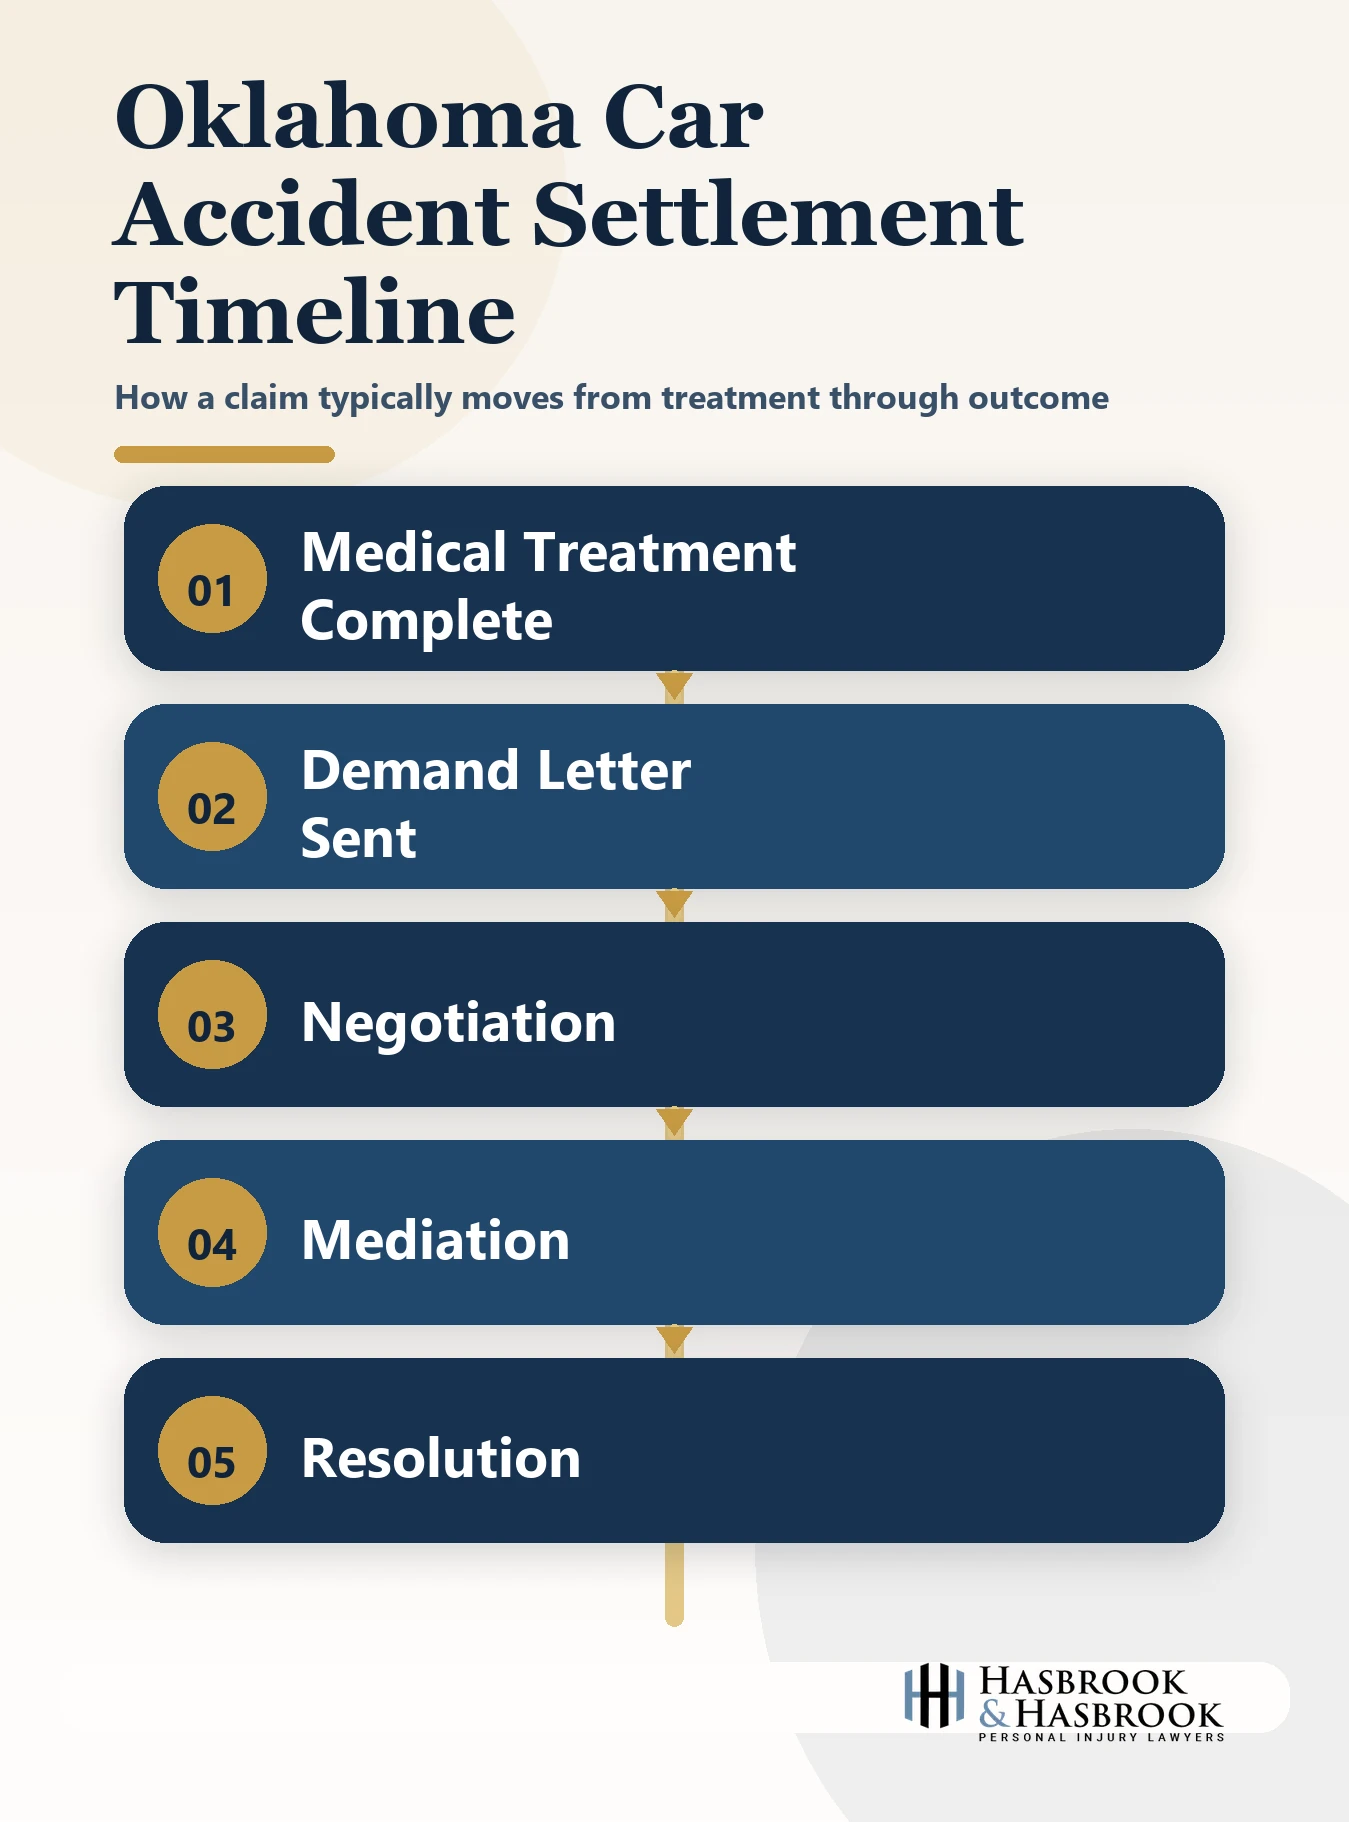
Most Oklahoma car accident settlements move through these stages:
- Seek medical treatment and document everything. Your records are the evidentiary foundation of your claim; gaps in treatment give adjusters an argument that your injuries were not serious. See what to preserve in your treatment records.
- File your claim and hire an attorney. Notify the at-fault driver’s insurer and retain counsel, who then handles all carrier communications. See the step-by-step claims workflow after a wreck.
- Complete or stabilize treatment. Demanding too early risks undervaluing future needs, so your attorney typically waits until you reach maximum medical improvement.
- Send the demand letter. Your attorney sets out the accident facts, injuries, treatment, and economic losses, with a demand figure set above the expected settlement to leave room for negotiation. See what happens once that letter reaches the insurer.
- Negotiate. The insurer responds with a counteroffer, and multiple rounds typically follow. Understanding what your attorney is doing at the negotiating table helps set realistic expectations.
- Settle or file suit. If negotiations reach a fair number, you sign a release and receive payment; if not, your attorney files suit, and most of those cases still resolve during discovery or mediation. See the filing-to-verdict litigation roadmap.
How much of a $100,000 settlement will you keep?
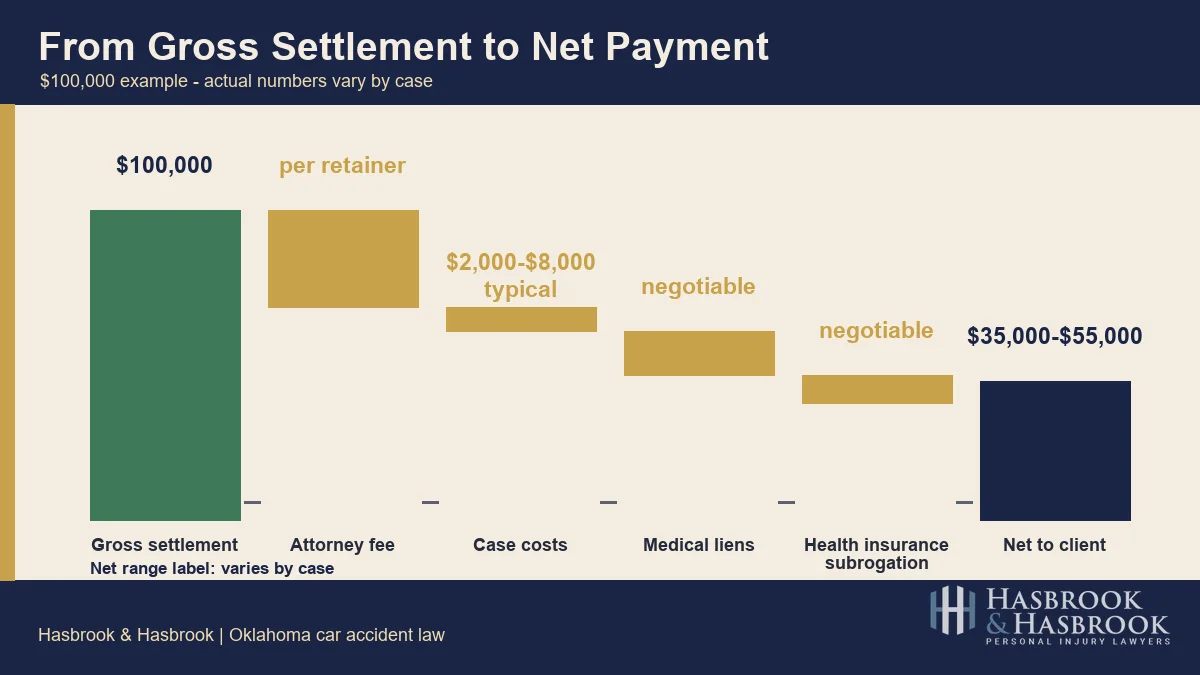
The gross settlement is not the amount deposited in your account; attorney fees, case costs, and medical liens are deducted first. Here is what those deductions look like on a hypothetical $100,000 gross settlement:
| Item | Notes |
|---|---|
| Gross settlement | $100,000 |
| Attorney’s contingency fee | Per your retainer agreement; review your retainer for the specific rate |
| Case costs | Filing fees, records, depositions, expert fees (typically $2,000 to $8,000 on a $100,000 case) |
| Medical liens (provider or hospital) | Negotiable; lien reductions directly increase your net recovery |
| Health insurance subrogation | Your health insurer may seek reimbursement for bills it paid; also negotiable in most cases |
| Sample net to client (varies by case) | Typically $35,000 to $55,000 on a $100,000 gross (roughly 35% to 55% of gross), depending on retainer rate, case costs, and lien negotiation outcomes |
This range is illustrative, not a guarantee. Your actual net depends on your retainer terms, the specific liens against your case, and how much those liens can be reduced. Ask your attorney for a case-specific projection.
Medical liens. Oklahoma hospitals, physicians, and health insurers can file liens against your settlement, which must be satisfied before you receive the remainder; your attorney often negotiates those amounts down. See our checklist for identifying and resolving medical liens and background on why a treating provider may file a lien.
Medicare and Medicaid liens. If Medicare or Medicaid paid any of your bills, federal law requires reimbursement from your settlement; it is not optional, though the amount can sometimes be reduced. See our guide to resolving federal-payer liens.
Typical Oklahoma car accident settlement timeline
Settlement timelines depend on injury complexity, whether liability is disputed, and how cooperative the insurer is. These are typical ranges, not guarantees:
| Phase | Typical Duration |
|---|---|
| Medical treatment and stabilization | 1 month to 2+ years depending on injury |
| Demand letter preparation after MMI | 2 to 6 weeks |
| Insurer review and first response to demand | 30 to 60 days |
| Negotiation rounds | 30 to 90 additional days |
| Litigation through discovery (if no settlement) | 6 to 18 months after filing |
| Mediation (if ordered or agreed) | Scheduled by court or mutual agreement |
Simple cases with clear liability resolve in 3 to 6 months; cases involving surgery, permanent impairment, or disputed liability regularly take 18 months or longer. See what actually controls how fast your case moves.

Why some cases go to trial instead of settling
Cases that resist settlement typically involve one or more of these:
- Policy limits too low. The at-fault driver’s coverage falls far short of actual damages, and the insurer will not engage on excess exposure.
- Disputed liability. The insurer argues your fault exceeds 50 percent, which would bar recovery entirely.
- Adjuster bad faith. The carrier unreasonably delays or undervalues your claim. Read about how an insurer’s bad-faith conduct changes a claim’s exposure.
- Refusal to tender policy limits. When damages clearly exceed the policy and the insurer will not offer its full limits, litigation may be the only path to full recovery.
See our page on weighing a settlement against taking your case to trial and the trade-offs of resolving a claim before it reaches a jury for a fuller comparison.
How comparative fault reduces your recovery
Oklahoma follows a modified comparative fault rule under 23 O.S. § 13: your recovery is reduced by your percentage of fault, and barred entirely once your fault exceeds 50 percent.
Example: A jury awards $100,000 but finds you 25 percent at fault and the other driver 75 percent at fault. Your recovery is reduced to $75,000. Had the jury found you 55 percent at fault, you would receive nothing.
Adjusters factor their estimated fault percentage into every offer. Your attorney counters with the accident reconstruction report, police report, and witness statements to challenge that allocation.
What a skilled attorney adds to your settlement
An attorney who regularly handles Oklahoma car accident cases affects both your gross settlement and your net recovery: identifying losses unrepresented claimants miss, including MedPay subrogation rights and the value a repaired vehicle loses even after it’s fixed, negotiating medical liens down, and credibly threatening trial. Adjusters track which firms actually try cases; firms that always settle short of trial give insurers little reason to offer full value. Reported data consistently shows that represented claimants recover more, on average, than unrepresented ones, typically by more than enough to offset the fee.
If you have questions about your case, contact Hasbrook & Hasbrook at (405) 605-2426. Initial consultations are free, and we work on contingency, meaning you pay nothing unless we recover for you.
Frequently asked questions about Oklahoma car accident settlements
How is a car accident settlement calculated in Oklahoma?
Gross settlement equals economic damages (medical bills, lost wages, property damage) plus non-economic damages (pain and suffering), reduced by fees, costs, and liens before you are paid. See the categories of damages available after a wreck.
How long do I have to file a car accident claim in Oklahoma?
Generally two years from the accident date under 12 O.S. § 95, though limited tolling exceptions apply in some circumstances.
Can I recover compensation if I was partly at fault?
Yes, unless your fault exceeds 50 percent. Oklahoma’s rule reduces your recovery by your fault percentage but bars it only once your fault exceeds everyone else’s combined.
What types of damages can I recover?
Economic damages (medical bills, lost wages, property damage, future medical costs) and non-economic damages (pain and suffering, emotional distress). Punitive damages may apply where conduct was reckless or intentional, though that is uncommon in standard collisions.
Should I accept the insurance company’s first settlement offer?
Rarely. First offers are designed to close the claim before you understand your full injuries and future costs. Have an attorney review any offer first. See what to weigh before signing a release and our FAQ on how to tell whether an offer undervalues your claim.
Are car accident settlement proceeds taxable in Oklahoma?
Compensation for physical injuries is generally not taxable under federal law, per IRS Publication 4345, or under Oklahoma income tax, though punitive damages and pre-judgment interest may be taxable. See which parts of a settlement the IRS can tax.


Talk to an Oklahoma City Car Accident Attorney About Your Settlement
Injury severity, policy limits, comparative fault, and lien negotiation all move the final number, and the gross figure an insurer offers is never what you keep. Call Hasbrook & Hasbrook at (405) 605-2426 for a free review of your accident facts, records, and any offer already on the table.